Roth IRA 2026: New Limits & Contribution Strategies
Anúncios
Understanding and adapting to the new income limits and contribution strategies for Roth IRAs in 2026 is crucial for individuals aiming to optimize their tax-free retirement savings.
Anúncios
Are you ready to elevate your retirement planning? Optimizing Your Roth IRA in 2026: New Income Limits and Contribution Strategies is more critical than ever. With evolving financial landscapes, staying informed about the latest changes can significantly impact your long-term wealth accumulation.
Understanding the Roth IRA Landscape in 2026
The Roth IRA continues to be a cornerstone of retirement planning for many, offering tax-free withdrawals in retirement. However, its utility is highly dependent on current tax laws and economic conditions. As we look towards 2026, several adjustments are anticipated, making it essential to re-evaluate your approach to this powerful savings vehicle.
These adjustments typically include changes to income thresholds that determine eligibility for direct contributions, as well as potential shifts in contribution limits. Understanding these foundational elements is the first step toward crafting an effective Roth IRA strategy. Without a clear grasp of these parameters, individuals might inadvertently miss out on opportunities or, worse, make ineligible contributions.
Anúncios
Key regulatory changes expected
- Annual inflation adjustments to contribution limits.
- Revised Modified Adjusted Gross Income (MAGI) thresholds for eligibility.
- Potential legislative updates influencing retirement accounts.
The evolving nature of tax legislation means that what held true last year might not apply in 2026. Therefore, a proactive stance in understanding these regulatory shifts is not just advisable, but necessary for maximizing the benefits of your Roth IRA. This section aims to provide a clear overview of what to expect, setting the stage for more detailed strategic discussions.
In essence, staying current with the Roth IRA landscape for 2026 means being aware of both the incremental, inflation-driven changes and any larger legislative reforms. This knowledge empowers you to make informed decisions that align with your financial goals and current regulations.
Navigating the New Income Limits for 2026
One of the most significant factors influencing Roth IRA eligibility is the Modified Adjusted Gross Income (MAGI) limit. For 2026, these limits are projected to increase, reflecting inflationary pressures and economic growth. These adjustments are crucial because exceeding the MAGI limit can either restrict your ability to contribute directly or prevent it entirely, pushing you towards alternative strategies like the ‘Backdoor Roth’.
It’s important to differentiate between the income phase-out ranges for single filers, married filing jointly, and those married filing separately. Each category typically has distinct thresholds. Understanding where you fall within these ranges will dictate your direct contribution eligibility and whether you need to consider more complex strategies.
Projected MAGI thresholds and their impact
While official numbers are usually released closer to the end of the preceding year, financial experts often provide projections based on historical data and economic forecasts. These projections can offer a valuable early look at what to expect.
- Single Filers: Anticipate a higher income phase-out range.
- Married Filing Jointly: Expect a corresponding increase in their combined income limits.
- Married Filing Separately: These limits often remain lower and can be more restrictive.
Exceeding the MAGI limits does not necessarily mean a Roth IRA is out of reach. It simply means the direct contribution path might be closed, necessitating a different approach. This is where strategic planning becomes paramount, ensuring that you can still benefit from the Roth IRA’s tax-free growth even with higher earnings.
Ultimately, a careful review of your projected income for 2026 against these new limits is essential. This early assessment allows you to plan your contributions effectively, avoiding any surprises or missed opportunities as the year progresses.
Optimizing Contribution Strategies for Maximum Benefit
Beyond simply meeting the eligibility criteria, truly optimizing your Roth IRA in 2026 involves strategic thinking about how and when you contribute. For many, simply contributing the maximum allowed amount is the goal, but there are nuances that can enhance the long-term benefits.
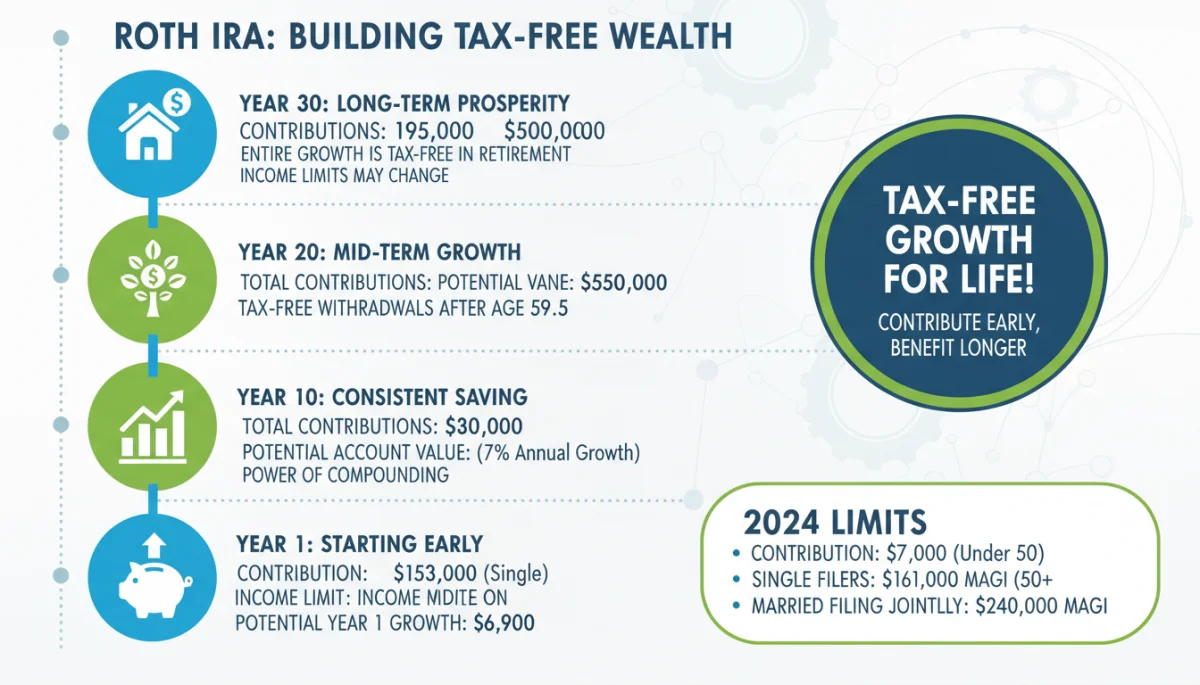
One key strategy is to contribute early in the year. By front-loading your contributions, your money has more time to grow tax-free over the course of the year. This compounding effect, even for a few extra months each year, can add up significantly over decades, especially in volatile markets where early investment can capture upturns.
Strategies for different income levels
Your income level plays a crucial role in determining the most effective contribution strategy. For those comfortably within the MAGI limits, direct contributions are straightforward. However, for high-income earners, the ‘Backdoor Roth IRA’ remains a vital tool.
The Backdoor Roth involves contributing to a traditional IRA and then converting it to a Roth IRA. This strategy bypasses the direct income limits, allowing high earners to still enjoy the benefits of tax-free growth and withdrawals. It requires careful execution to avoid tax pitfalls, particularly the ‘pro-rata rule’ if you hold other pre-tax IRA accounts.
- Direct Contributions: Ideal for those below MAGI limits.
- Backdoor Roth: Essential for high-income earners to bypass limits.
- Spousal Roth IRA: Allows a non-working spouse to contribute.
Another often-overlooked strategy is dollar-cost averaging. While front-loading is generally preferred for Roth IRAs due to the long-term compounding, consistent contributions throughout the year can smooth out market fluctuations and reduce the risk of investing a lump sum at an inopportune time. The best approach often depends on individual financial circumstances and market outlook.
Ultimately, the optimal contribution strategy is one that is consistent, maximizes your allowable contributions, and aligns with your overall financial plan. Whether through direct contributions, a backdoor conversion, or a spousal IRA, the goal is to get as much money into the Roth as possible, as early as possible.
The Backdoor Roth IRA: A High-Income Earner’s Guide
For high-income individuals who exceed the direct contribution limits for a Roth IRA, the Backdoor Roth IRA strategy is an indispensable tool. This method allows you to contribute indirectly to a Roth, leveraging its tax-free growth and withdrawals, even when your MAGI is too high for direct contributions. It’s a perfectly legal and IRS-sanctioned maneuver, but it requires careful execution.
The process typically involves two main steps: first, making a non-deductible contribution to a traditional IRA, and second, converting that traditional IRA to a Roth IRA. The key to this strategy is that the initial contribution to the traditional IRA is non-deductible, meaning you don’t receive a tax break for it, but it also means the conversion itself won’t be a taxable event (assuming certain conditions are met).
Avoiding pitfalls with the pro-rata rule
The most common pitfall in executing a Backdoor Roth is the ‘pro-rata rule’. This rule comes into play if you have existing pre-tax funds in any traditional, SEP, or SIMPLE IRA accounts. If you do, a portion of your conversion will be taxable, even if your recent contribution was non-deductible.
- Consolidate IRAs: Consider rolling pre-tax IRA funds into a 401(k) or similar employer-sponsored plan before conversion.
- No Existing Pre-Tax IRAs: The Backdoor Roth is simplest and most tax-efficient if you have no other pre-tax IRA balances.
- Timely Conversion: Convert the non-deductible contribution to a Roth IRA as quickly as possible to minimize any potential gains on the non-deductible amount before conversion, which would be taxable.
Documentation is also critical. Ensure you accurately report your non-deductible contributions on Form 8606 with your tax return. This form tracks your basis in non-deductible IRA contributions, which is essential for proving that the converted funds were already taxed and should not be taxed again upon conversion.
While the Backdoor Roth IRA offers a valuable path for high-income earners, it demands a thorough understanding of the rules and careful execution to avoid unintended tax consequences. Consulting with a qualified financial advisor or tax professional is highly recommended to ensure the strategy is implemented correctly for your specific situation.
Roth IRA vs. Traditional IRA: Which is Right for You in 2026?
Deciding between a Roth IRA and a Traditional IRA is a fundamental decision in retirement planning, and the optimal choice often depends on your current income, anticipated future income, and tax outlook. Both offer significant tax advantages, but they differ in when those advantages are realized.
A Traditional IRA offers tax-deductible contributions, meaning you get a tax break in the present. Your investments grow tax-deferred, but withdrawals in retirement are taxed as ordinary income. This structure is generally more beneficial if you expect to be in a lower tax bracket in retirement than you are today.
Key differences and considerations
The Roth IRA, on the other hand, offers no upfront tax deduction for contributions. However, your investments grow tax-free, and qualified withdrawals in retirement are also tax-free. This is particularly advantageous if you anticipate being in a higher tax bracket in retirement or if you value the certainty of tax-free income in your later years.
- Tax Timing: Traditional IRA offers upfront tax deduction; Roth IRA offers tax-free withdrawals.
- Income Limits: Roth IRA has MAGI limits for direct contributions; Traditional IRA has income limits for deductibility, but not for contributions.
- Required Minimum Distributions (RMDs): Traditional IRAs have RMDs starting at age 73; Roth IRAs do not have RMDs for the original owner.
For 2026, consider how potential changes in tax policy might affect your decision. If tax rates are expected to rise in the future, a Roth IRA becomes even more attractive. Conversely, if you are currently in a very high tax bracket and expect to drop significantly in retirement, a Traditional IRA might offer more immediate tax savings.
Many individuals also choose to diversify by contributing to both a Traditional and a Roth IRA, hedging against future tax uncertainties. This strategy provides flexibility, allowing you to draw from whichever account offers the most tax-efficient withdrawals in retirement, depending on your financial situation at that time.
Ultimately, the best choice depends on a thorough analysis of your personal financial situation, tax bracket, and long-term retirement goals. It’s not a one-size-fits-all answer and may evolve over time.
Strategies for Maximizing Roth IRA Growth Beyond Contributions
While understanding income limits and making consistent contributions are fundamental, maximizing your Roth IRA strategies 2026 extends beyond just putting money in. The true power of a Roth IRA lies in its tax-free growth, which can be significantly amplified by smart investment choices and proactive management.
The investment vehicles you choose within your Roth IRA are paramount. Growth-oriented assets like equities, exchange-traded funds (ETFs), and certain mutual funds are often preferred due to the long-term nature of retirement planning. Since all qualified withdrawals are tax-free, any substantial gains you realize over decades will remain untouched by the IRS, making growth a top priority.
Investment selection and rebalancing
Diversification is key within your Roth IRA portfolio. Spreading your investments across different asset classes, industries, and geographies helps mitigate risk while still pursuing strong returns. Avoid putting all your eggs in one basket, even if that basket seems promising in the short term.
- Equity Focus: Prioritize stocks or stock-based funds for long-term growth potential.
- Diversification: Spread investments across various sectors and asset types.
- Regular Rebalancing: Periodically adjust your portfolio to maintain your desired asset allocation.
Regularly reviewing and rebalancing your portfolio is also critical. As market conditions change and certain investments outperform others, your asset allocation can drift from your target. Rebalancing ensures you sell off some of your winners to buy more of your underperformers, maintaining your risk profile and potentially boosting future returns. This disciplined approach prevents your portfolio from becoming overly concentrated in one area.
Consider also the impact of compound interest. The longer your money is invested, the more it can grow exponentially. Therefore, starting early and maintaining a consistent investment strategy within your Roth IRA are perhaps the most powerful tools for maximizing its long-term value. Even small, consistent contributions can become substantial sums over several decades.
By focusing on strategic investment selection, diligent diversification, and consistent rebalancing, you can ensure your Roth IRA is not just a savings account, but a powerful engine for wealth creation, truly optimizing its tax-free growth potential.
Common Misconceptions and How to Avoid Them in 2026
Despite its popularity, the Roth IRA is often misunderstood, leading to common errors that can hinder its effectiveness. As we approach 2026, it’s vital to clarify these misconceptions to ensure you’re fully leveraging this powerful retirement tool without falling into traps.
One prevalent misconception is that once you contribute to a Roth IRA, your money is locked away until retirement. While it’s true that the primary purpose is long-term savings, contributions (not earnings) can be withdrawn tax-free and penalty-free at any time. This offers a degree of liquidity that many other retirement accounts lack, making it a flexible option for emergency savings, though it’s generally not advisable to tap into retirement funds prematurely.
Avoiding common Roth IRA mistakes
Another common mistake is failing to understand the five-year rules. There are two distinct five-year rules for Roth IRAs: one for contributions and one for conversions. To withdraw earnings tax-free and penalty-free, your Roth IRA must be open for at least five years AND you must meet one of several conditions (e.g., age 59½, disability, first-time home purchase).
- Not understanding withdrawal rules: Differentiate between contributions and earnings for tax-free withdrawals.
- Ignoring the five-year rules: Be aware of the two distinct five-year periods for tax-free earnings withdrawals.
- Incorrectly executing backdoor Roth conversions: Ensure proper reporting and avoid the pro-rata rule.
Some individuals also mistakenly believe that a Roth IRA is only for younger, lower-income individuals. While it’s incredibly beneficial for those starting their careers, the Backdoor Roth IRA strategy ensures that even high-income earners can participate. Furthermore, the absence of Required Minimum Distributions (RMDs) for the original owner makes it an excellent estate planning tool, as funds can continue to grow tax-free for beneficiaries.
Finally, overlooking the importance of beneficiary designations is a significant oversight. Properly naming beneficiaries ensures your Roth IRA assets pass smoothly according to your wishes, potentially maximizing tax benefits for your heirs. Regularly review and update these designations, especially after major life events.
By dispelling these common myths and understanding the nuances of Roth IRA rules, you can ensure your retirement savings strategy for 2026 is robust, compliant, and optimized for your financial future.
| Key Aspect | Description for 2026 |
|---|---|
| New Income Limits | Projected increases in Modified Adjusted Gross Income (MAGI) thresholds will impact direct contribution eligibility. |
| Contribution Strategies | Early contributions, Backdoor Roth for high earners, and spousal IRAs are key for maximizing savings. |
| Backdoor Roth IRA | A crucial method for high-income earners to bypass MAGI limits, requiring careful execution to avoid tax issues. |
| Investment Growth | Strategic investment selection, diversification, and regular rebalancing are vital for tax-free wealth accumulation. |
Frequently Asked Questions About Roth IRAs in 2026
While official figures are typically released later, projections suggest an increase in Modified Adjusted Gross Income (MAGI) limits for 2026 due to inflation. These new thresholds will determine eligibility for direct contributions, impacting single filers and those married filing jointly. Always verify official IRS announcements for precise numbers.
If your income exceeds the direct contribution limits, you can utilize the ‘Backdoor Roth IRA’ strategy. This involves making a non-deductible contribution to a Traditional IRA and then converting it to a Roth IRA. It’s a legal method, but requires careful attention to the pro-rata rule to avoid unexpected tax implications.
The choice between a Roth and Traditional IRA in 2026 depends on your current and projected future tax bracket. A Roth is typically better if you expect to be in a higher tax bracket in retirement, offering tax-free withdrawals. A Traditional IRA provides an upfront tax deduction, suitable if you anticipate a lower tax bracket later.
There are two distinct five-year rules. One applies to the first Roth IRA contribution, meaning your account must be open for five years before earnings can be withdrawn tax-free. The other applies to conversions. Both must be satisfied, along with other conditions like being over age 59½, for qualified tax-free and penalty-free earnings withdrawals.
To maximize Roth IRA growth, focus on growth-oriented investments like diversified equities or ETFs, as all qualified earnings are tax-free. Regular rebalancing ensures your portfolio stays aligned with your risk tolerance and financial goals. Starting early allows for greater compounding, significantly boosting your tax-free wealth over time.
Conclusion
As we navigate the financial landscape of 2026, understanding and strategically applying the insights presented regarding Roth IRAs is paramount for securing a robust retirement. The anticipated shifts in income limits and the continued relevance of strategies like the Backdoor Roth underscore the need for proactive financial planning. By staying informed about regulatory changes, optimizing your contributions, making savvy investment choices, and avoiding common pitfalls, you can fully harness the tax-free growth potential of your Roth IRA. This powerful tool, when managed thoughtfully, remains an invaluable asset in building a resilient financial future.
