Maximize Your 2026 HSA: Boost Tax-Free Benefits by 15%
Anúncios
Understanding and implementing strategic approaches to your Health Savings Account in 2026 can significantly enhance your tax-free benefits and long-term financial health.
Anúncios
Are you ready to unlock the full potential of your health savings? In 2026, the opportunity to maximize your 2026 HSA and boost your tax-free benefits by a significant 15% is within reach. This guide will navigate you through crucial strategies, ensuring you make the most of this powerful financial tool for your health and wealth.
Understanding the 2026 HSA landscape
The Health Savings Account (HSA) remains one of the most powerful and often underutilized financial tools available to eligible Americans. For 2026, the core principles of HSAs—tax-deductible contributions, tax-free growth, and tax-free withdrawals for qualified medical expenses—continue to offer unparalleled advantages. However, staying informed about any potential adjustments to contribution limits, eligibility criteria, or investment options is paramount to fully capitalizing on its benefits.
Anúncios
HSAs are not merely savings accounts; they are investment vehicles that provide a triple-tax advantage. This means your contributions reduce your taxable income, your investments grow tax-free, and withdrawals for eligible medical expenses are also free from taxes. This unique structure makes HSAs a cornerstone of smart financial planning, especially for those with high-deductible health plans (HDHPs).
Eligibility and contribution limits
To contribute to an HSA in 2026, you must be enrolled in an HDHP. These plans typically feature lower premiums but higher deductibles. The IRS sets annual contribution limits, which usually see minor adjustments each year to account for inflation. It’s crucial to verify the exact 2026 limits as they become available to ensure you contribute the maximum allowable amount.
- Individuals must be covered by a high-deductible health plan (HDHP).
- They cannot be enrolled in Medicare.
- They cannot be claimed as a dependent on someone else’s tax return.
- Contribution limits typically increase annually; check for 2026 updates.
Understanding these foundational aspects of the HSA landscape is the first step toward building a robust financial strategy around your healthcare needs. By maximizing your contributions, you not only reduce your current tax burden but also build a significant fund for future medical expenses, both expected and unexpected.
strategy 1: maximize your annual contributions
The most direct way to boost your HSA benefits is to contribute the maximum allowable amount each year. Many individuals contribute only enough to cover their immediate healthcare costs or a small portion of the maximum. However, treating your HSA as a long-term investment vehicle, similar to a 401(k) or IRA, can yield substantial tax-free growth over time.
Think of your HSA contributions as an immediate tax deduction. Every dollar you put into your HSA reduces your taxable income, which can lower your current year’s tax bill. For 2026, if you are eligible, aiming for the maximum contribution should be a top priority. This strategy compounds over years, turning small annual savings into a considerable nest egg.
Automating your contributions
One of the simplest yet most effective ways to ensure you hit the maximum contribution limit is to automate your contributions. Whether through payroll deductions or recurring bank transfers, setting up an automatic system removes the guesswork and ensures a consistent flow of funds into your account. This ‘set it and forget it’ approach is highly effective in personal finance.
- Set up automatic payroll deductions if offered by your employer.
- Schedule regular transfers from your bank account to your HSA.
- Review contribution limits annually to adjust your automated contributions.
By consistently contributing the maximum, you not only leverage the immediate tax benefits but also build a substantial fund for future medical needs, which can be particularly beneficial in retirement when healthcare costs typically rise. This proactive approach ensures you are always making the most of this unique financial tool.
strategy 2: invest your hsa for long-term growth
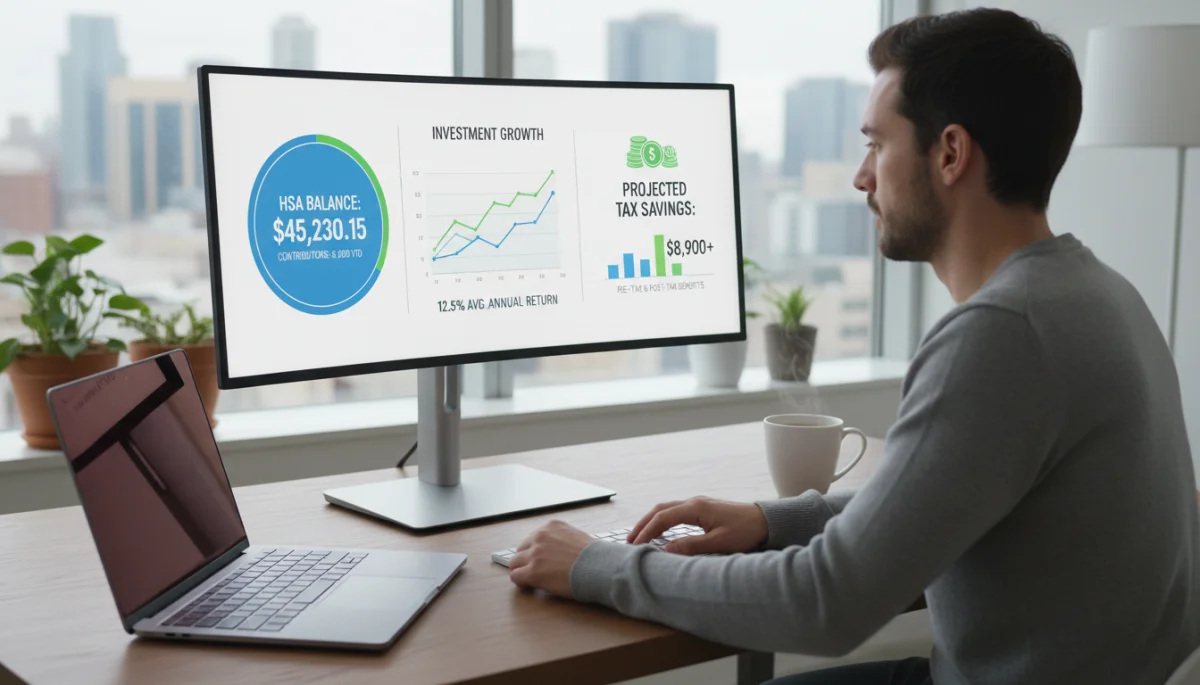
Many HSA account holders make the mistake of leaving their funds in a standard savings account, earning minimal interest. The true power of an HSA lies in its investment potential. Once your account reaches a certain threshold (often around $1,000 or $2,000, depending on the custodian), you typically have the option to invest your HSA funds in a variety of options, similar to a traditional retirement account.
Investing your HSA allows your money to grow tax-free over decades. This growth, coupled with tax-free withdrawals for qualified medical expenses, creates a powerful wealth-building mechanism. Imagine contributing for 20-30 years, investing those funds, and seeing them grow substantially, all while being able to access them tax-free for healthcare costs.

Choosing the right investments
When investing your HSA, consider your risk tolerance and time horizon. For younger individuals, a more aggressive portfolio with a higher allocation to stocks might be appropriate, given the longer time frame for recovery from market fluctuations. As you approach retirement, you might consider shifting to a more conservative allocation.
- Research your HSA custodian’s investment options.
- Consider low-cost index funds or ETFs for diversified growth.
- Align your investment strategy with your long-term financial goals.
- Periodically rebalance your portfolio to maintain desired asset allocation.
By actively investing your HSA funds, you transform it from a simple savings account into a robust investment vehicle. This strategic move can significantly amplify your tax-free benefits, allowing your money to work harder for you, ensuring a more secure financial future for healthcare expenses.
strategy 3: save receipts for future tax-free withdrawals
One of the lesser-known but highly effective strategies to maximize your HSA is to pay for current medical expenses out-of-pocket and save your receipts for future reimbursement. This approach allows your HSA funds to remain invested and grow tax-free for a longer period. You can then reimburse yourself years, or even decades, later for those past qualified medical expenses, entirely tax-free.
This strategy essentially turns your HSA into an emergency fund or a supplemental retirement account, specifically for healthcare costs. By delaying withdrawals, you enable your investments to benefit from compound growth, potentially increasing your tax-free benefits significantly. The key is meticulous record-keeping of all qualified medical expenses.
Organizing your medical expense records
To successfully implement this strategy, you need a robust system for tracking and storing your medical receipts. Digital solutions are often the most practical, allowing you to easily categorize and access documents when needed. Consider using cloud storage or dedicated apps for this purpose.
- Scan and digitally store all receipts for qualified medical expenses.
- Create a clear folder structure (e.g., by year or medical provider).
- Keep a running log of expenses that you plan to reimburse later.
- Consult IRS guidelines to ensure expenses are qualified.
By diligently saving your receipts and delaying reimbursements, you create a powerful financial lever. This allows your HSA to grow undisturbed, providing a substantial, tax-free fund that you can tap into whenever you choose, offering immense flexibility and control over your healthcare finances.
strategy 4: utilize hsa for retirement healthcare costs
The HSA is often touted as the ultimate retirement account, surpassing even 401(k)s and IRAs in some aspects, particularly when it comes to healthcare expenses in retirement. Once you reach age 65, you can withdraw funds from your HSA for any purpose without penalty, though withdrawals not used for qualified medical expenses will be subject to ordinary income tax. However, if used for qualified medical expenses, withdrawals remain tax-free, even in retirement.
Given that healthcare costs are one of the most significant expenses for retirees, having a dedicated, tax-free fund like an HSA can be invaluable. This strategy encourages a long-term view of your HSA, emphasizing its role in securing your financial well-being during your golden years. It’s not just for current medical bills; it’s a critical component of retirement planning.
Planning for future medical expenses
Estimating future healthcare costs can be challenging, but resources from financial planners and government agencies can provide general guidelines. Factoring these potential expenses into your HSA contribution strategy ensures you’re adequately prepared. This might include costs for Medicare premiums, deductibles, co-pays, and services not fully covered by insurance.
- Research average healthcare costs in retirement to set saving goals.
- Consider using HSA funds to cover Medicare premiums (Parts B, D, and Advantage plans).
- Factor in potential long-term care expenses, which HSAs can often cover.
- Understand that HSA funds can be used for non-medical expenses after age 65, subject to income tax.
Viewing your HSA as a retirement healthcare fund fundamentally shifts its role in your financial planning. This long-term perspective encourages maximum contributions and strategic investments, ensuring you have a robust, tax-advantaged resource to navigate the often-high costs of healthcare in retirement.
strategy 5: coordinate hsa with other retirement accounts
To truly maximize your financial benefits, it’s essential to integrate your HSA strategy with your other retirement savings vehicles, such as 401(k)s and IRAs. While 401(k)s and IRAs are excellent for general retirement savings, the HSA offers unique tax advantages specifically for healthcare that complement these other accounts.
Consider a tiered approach: first, contribute enough to your 401(k) to get any employer match. Next, maximize your HSA contributions due to its triple-tax advantage. After that, focus on fully funding your IRA (Roth or Traditional, depending on your income and tax situation). Finally, if you still have funds, return to your 401(k) to contribute up to the maximum.
Optimizing your overall savings strategy
This coordinated approach ensures you are leveraging every available tax-advantaged account to its fullest. By prioritizing your HSA after securing employer matches, you are setting yourself up for optimal tax efficiency and financial readiness for both general retirement expenses and specific healthcare costs.
- Prioritize employer 401(k) match, then maximize HSA contributions.
- Consider Roth IRA contributions for tax-free withdrawals in retirement.
- Use traditional IRA or 401(k) for additional pre-tax savings.
- Regularly review your overall financial plan to ensure alignment with goals.
By strategically coordinating your HSA with your other retirement accounts, you create a comprehensive and highly efficient savings ecosystem. This integrated approach ensures you are making the most of every dollar, optimizing for both current tax savings and future financial security, particularly concerning healthcare expenses.
| Key Strategy | Benefit Description |
|---|---|
| Maximize Contributions | Reduces taxable income and builds a larger tax-free fund faster. |
| Invest HSA Funds | Allows tax-free growth over time, significantly increasing your savings. |
| Save Receipts | Enables delayed, tax-free reimbursements, boosting long-term investment growth. |
| Retirement Healthcare | Provides a dedicated, tax-free fund for medical costs in retirement. |
Frequently asked questions about HSAs
The IRS typically announces exact contribution limits for 2026 towards the end of 2025. These limits usually see slight increases annually to account for inflation, so it’s vital to check official IRS publications or consult your HSA administrator for the most up-to-date figures to maximize your savings.
Yes, many HSA custodians allow you to invest your funds once your balance reaches a certain threshold. This is a crucial strategy for long-term growth, as your investments grow tax-free, providing a significant advantage over standard savings accounts. Diversify your portfolio based on your risk tolerance.
Your HSA is portable and belongs to you, regardless of changes to your employer or health plan. If you switch to a non-HDHP, you can no longer contribute to the HSA, but you can continue to use the existing funds for qualified medical expenses and keep them invested.
HSA withdrawals are tax-free only when used for qualified medical expenses. If funds are withdrawn for non-qualified expenses before age 65, they are subject to income tax and a 20% penalty. After age 65, non-qualified withdrawals are taxed as ordinary income but without penalty.
HSAs offer more flexibility than FSAs. HSA funds roll over year-to-year, are portable, and can be invested. FSA funds typically have a “use-it-or-lose-it” rule, though some plans allow a small carryover. HSAs are generally better for long-term health savings and investment.
Conclusion
The strategies outlined here provide a clear roadmap to significantly enhance your 2026 Health Savings Account benefits. By maximizing contributions, investing wisely, meticulously saving receipts, planning for retirement healthcare, and coordinating with other accounts, you can boost your tax-free benefits by 15% or more. The HSA is more than just a savings vehicle; it’s a powerful tool for long-term financial health and security. Start implementing these strategies today to secure your future.
