2026 Disability Insurance Benefits: Protecting Your Income
Anúncios
Navigating 2026 disability insurance benefits is crucial for protecting your income, with policies typically covering up to 60% of earnings during periods of incapacitation.
Are you prepared for the unexpected? Securing your financial future means understanding how to protect your most valuable asset: your ability to earn an income. In 2026, comprehending your 2026 disability insurance benefits is more critical than ever to ensure you can protect up to 60% of your income if illness or injury prevents you from working.
Anúncios
The evolving landscape of disability insurance in 2026
Disability insurance is a cornerstone of financial planning, designed to replace a portion of your income if you become unable to work due to a covered disability. The year 2026 brings with it potential shifts in policy structures, regulatory frameworks, and economic factors that could influence your coverage.
Understanding these changes is vital for both new applicants and existing policyholders. The market is dynamic, and what was true a few years ago might not hold in the current environment. Staying informed helps you make educated decisions about your financial safety net.
Anúncios
Key regulatory considerations
Regulatory changes can significantly impact how disability insurance policies are structured and how benefits are paid. Federal and state laws are continually updated, and these adjustments often aim to protect consumers or adapt to economic realities.
- Consumer protection laws: New regulations might introduce enhanced protections for policyholders, affecting claim processes or benefit disputes.
- Tax implications: Changes in tax codes could alter how disability benefits are taxed, influencing your net income during a period of disability.
- State-specific mandates: Some states may introduce new requirements for insurers, potentially expanding coverage options or benefit levels.
These regulatory shifts underscore the importance of reviewing your policy annually and consulting with a financial advisor to ensure your coverage remains optimal. Ignoring these changes could lead to unexpected gaps in your financial protection when you need it most.
Types of disability insurance: short-term vs. long-term
Disability insurance typically comes in two primary forms: short-term disability (STD) and long-term disability (LTD). Each serves a distinct purpose, offering different durations and levels of income protection.
Knowing the difference and determining which type, or combination, best suits your needs is essential for comprehensive income protection. Many individuals find that a blend of both provides the most robust safety net.
Short-term disability (STD)
Short-term disability insurance provides benefits for a limited period, typically ranging from a few weeks to several months, often not exceeding one year. It’s designed to cover temporary incapacitations.
- Benefit period: Usually 3 to 6 months, though some policies extend to a year.
- Waiting period: Often 0 to 14 days before benefits begin.
- Coverage: Typically replaces 50% to 70% of your gross income.
STD is frequently offered as an employer-sponsored benefit, providing a crucial bridge for recovery from short-term illnesses, injuries, or even maternity leave. Understanding your employer’s STD policy is a key step in evaluating your overall coverage.
Long-term disability (LTD)
Long-term disability insurance kicks in after STD benefits expire, or after a longer waiting period, and can provide coverage for many years, up to retirement age, or even for life, depending on the policy. It’s designed for more severe or chronic conditions.
LTD policies are critical for protecting against life-altering disabilities that could prevent you from working for an extended duration. The financial impact of a long-term disability without adequate coverage can be devastating, making LTD a vital component of any robust financial plan.
Eligibility and claims process for 2026 benefits
Understanding the eligibility requirements and the claims process for your disability insurance benefits in 2026 is crucial for a smooth experience should you ever need to file a claim. Each policy will have specific definitions of disability and procedures to follow.
Don’t wait until you’re disabled to familiarize yourself with these details. Proactive knowledge can alleviate stress during an already challenging time and help ensure your claim is processed efficiently.
Defining disability
Most disability insurance policies define disability in one of two ways: ‘own occupation’ or ‘any occupation’. The definition significantly impacts your eligibility for benefits.
- Own occupation: You are considered disabled if you cannot perform the main duties of your specific job. This is generally more comprehensive and desirable.
- Any occupation: You are considered disabled if you cannot perform the duties of any occupation for which you are reasonably suited by education, training, or experience. This is a stricter definition.
Some policies may transition from ‘own occupation’ to ‘any occupation’ after a certain period, often 24 months. Always review your policy’s definition of disability carefully.
The claims process
Filing a disability claim involves several steps, and adherence to the insurer’s requirements is paramount. The process typically begins with notifying your insurer and submitting necessary documentation.
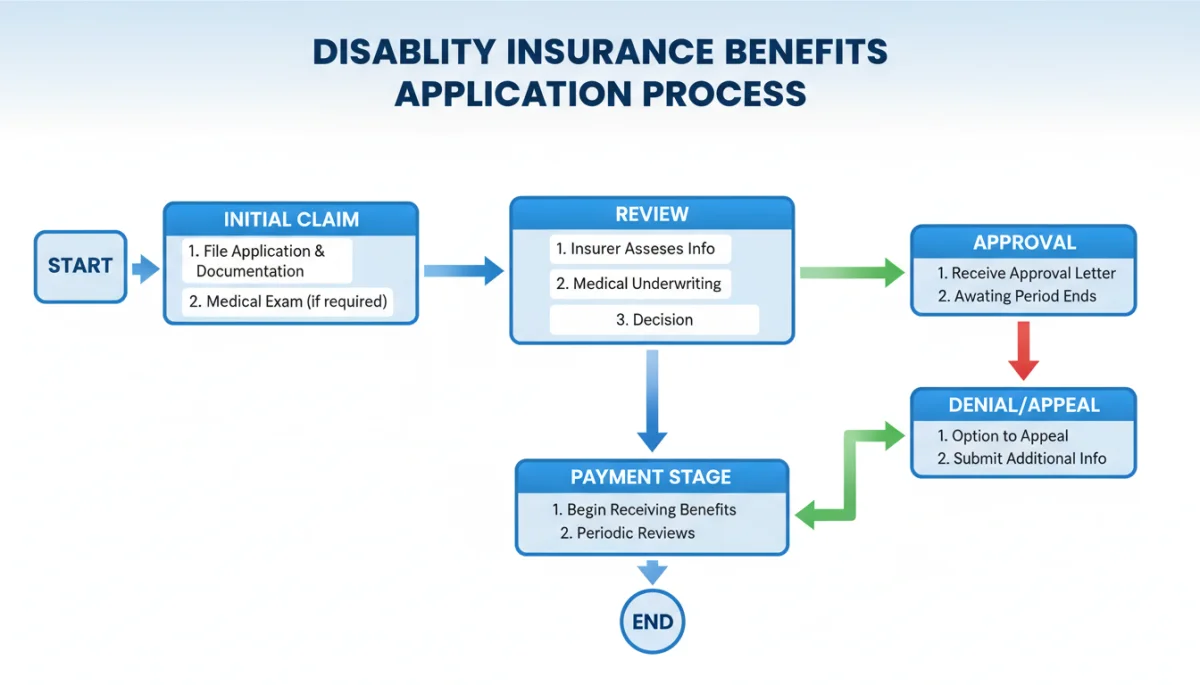

Key steps include:
- Notification: Inform your insurer as soon as possible after a disability occurs.
- Documentation: Provide medical records, employer statements, and other requested forms.
- Review: The insurer will review your claim, often involving independent medical examinations.
- Decision: The insurer will approve or deny your claim based on policy terms and evidence.
It’s important to maintain thorough records of all communications and medical documentation related to your disability. A well-organized approach can significantly expedite the claims process.
Maximizing your coverage: tips for 2026
Simply having a disability insurance policy isn’t enough; you need to ensure it provides adequate protection for your specific circumstances. In 2026, proactive steps can help you maximize your coverage and avoid potential pitfalls.
Regularly reviewing your policy and understanding its nuances can make a substantial difference in your financial security during a disability. Don’t assume your current coverage is sufficient without a thorough evaluation.
Reviewing your policy annually
Life changes, and so should your insurance coverage. An annual review of your disability insurance policy is crucial, especially as your income, expenses, and family situation evolve.
Consider the following during your review:
- Income changes: Has your salary increased significantly? Your current policy might not cover a sufficient percentage of your new income.
- Debt obligations: Have you taken on new debt, like a mortgage or student loans? Ensure your benefits can cover these payments.
- Family status: Have you married, had children, or experienced other life events that change your financial responsibilities?
Adjusting your coverage to reflect these changes ensures that your policy remains an effective safety net. Many policies offer riders or options to increase coverage without a new medical exam, making adjustments relatively straightforward.
Understanding policy riders and options
Disability insurance policies often come with various riders and options that can enhance your coverage. These add-ons can provide greater flexibility and protection, though they usually come with an additional cost.
Some common riders include:
- Cost of Living Adjustment (COLA) rider: Increases your benefits over time to keep pace with inflation.
- Future Increase Option (FIO) rider: Allows you to increase your coverage in the future without additional medical underwriting.
- Residual Disability rider: Provides partial benefits if you can work part-time but are still earning less due to your disability.
While these riders add to the premium, they can significantly improve the long-term value and effectiveness of your policy, providing peace of mind during extended periods of disability.
The financial impact of disability: why 60% coverage matters
Disability can have a profound financial impact, extending beyond just lost income. Medical expenses, rehabilitation costs, and lifestyle adjustments can quickly deplete savings if not adequately managed. Protecting up to 60% of your income through disability insurance is a common benchmark, and for good reason.
This percentage is often considered sufficient because disability benefits are typically tax-free if you pay the premiums with after-tax dollars. This means that 60% of your gross income might equate to a higher percentage of your net, take-home pay.
Beyond lost wages
The financial strain of a disability isn’t limited to your paycheck. Many other expenses can arise or intensify, putting immense pressure on your financial resources.
- Medical costs: Even with health insurance, co-pays, deductibles, and uncovered treatments can accumulate rapidly.
- Home modifications: If your disability requires changes to your living environment, such as ramps or accessible bathrooms, these can be costly.
- Care services: Depending on the severity, you might need assistance with daily living activities, which can incur significant expenses.
Disability insurance helps cover these indirect costs by providing a steady income stream, allowing you to focus on recovery rather than financial survival. It acts as a shield against the multifaceted economic consequences of an unexpected health event.
The 60% benchmark explained
The recommendation to cover around 60% of your gross income stems from several factors, primarily related to taxes and typical household expenses. When paid with after-tax dollars, disability benefits are generally not taxable.
For example, if your gross income is $5,000 per month, and your after-tax take-home pay is $3,500, a 60% benefit of $3,000 might replace a significant portion of your net income. This allows you to cover essential expenses without drastically altering your lifestyle.
It’s important to calculate your personal financial needs, including fixed expenses and discretionary spending, to determine if 60% coverage is truly adequate for your unique situation. Some individuals with high fixed costs or specific financial goals may opt for slightly higher coverage if available.
Choosing the right policy and provider in 2026
Selecting the right disability insurance policy and provider in 2026 involves careful consideration of various factors, from the insurer’s financial stability to the specifics of the policy’s terms and conditions. It’s a decision that can significantly impact your future financial security.
Don’t rush into a decision; thorough research and professional guidance are invaluable. A well-chosen policy from a reputable provider offers peace of mind and reliable protection.
Factors when choosing a provider
Not all insurance providers are created equal. When selecting an insurer, consider their reputation, financial strength, and customer service record.
- Financial stability: Look for insurers with high ratings from independent agencies like A.M. Best, Standard & Poor’s, or Moody’s. This indicates their ability to pay claims.
- Reputation: Research customer reviews and complaints to gauge their responsiveness and fairness in handling claims.
- Customer service: A responsive and helpful customer service team can make a significant difference during the claims process.
A provider’s track record in paying claims is a critical indicator of their reliability. Choose an insurer with a history of fair and timely benefit payouts.
Comparing policy features
Beyond the basic coverage, policies offer a range of features that can differentiate them. Comparing these features is key to finding a policy that aligns with your specific needs.
When comparing policies, pay attention to:
- Definition of disability: As discussed, ‘own occupation’ is generally preferred.
- Benefit period: How long will benefits be paid? Up to retirement age is ideal for LTD.
- Waiting period (elimination period): How long do you have to wait before benefits begin?
- Renewability: Is the policy non-cancellable and guaranteed renewable? This ensures your policy cannot be canceled or premiums raised (beyond scheduled increases) as long as you pay on time.
A detailed comparison of these features, ideally with the help of an independent insurance agent, will help you secure the most suitable and comprehensive coverage for your circumstances in 2026.
Integrating disability insurance with other financial plans
Disability insurance should not exist in isolation. It’s a critical component of a broader financial strategy, working in conjunction with savings, investments, and other insurance products to create a robust financial safety net.
Effective financial planning involves ensuring all parts of your plan work harmoniously, providing layers of protection against various risks. Integrating your disability insurance thoughtfully enhances your overall financial resilience.
Emergency savings and disability benefits
An emergency fund is your first line of defense against unexpected financial setbacks, including short waiting periods for disability benefits. Ideally, you should have 3-6 months of living expenses saved.
This fund can cover your expenses during the waiting period before your disability benefits kick in. Without it, even with a strong disability policy, you could face significant financial stress during the initial weeks or months of a disability.
Long-term financial goals and disability
A long-term disability can derail retirement savings, college funds, and other significant financial goals. Disability insurance helps keep these plans on track by replacing lost income.
If you’re unable to work, your disability benefits can ensure you continue to contribute to your retirement accounts or other investment vehicles, preventing a major setback in your long-term wealth accumulation. This seamless integration ensures that a health crisis doesn’t become a financial catastrophe for your future aspirations.
| Key Aspect | Brief Description |
|---|---|
| Income Protection | Disability insurance can replace up to 60% of your income if you cannot work due to illness or injury. |
| Policy Types | Short-term (STD) covers temporary disabilities; long-term (LTD) covers extended periods, often to retirement. |
| Eligibility & Claims | Understand ‘own occupation’ vs. ‘any occupation’ definitions and follow the insurer’s claim process diligently. |
| Maximizing Coverage | Review policies annually, consider riders like COLA or FIO, and integrate with overall financial planning. |
Frequently asked questions about 2026 disability insurance
It means your policy aims to replace up to 60% of your gross income if you become disabled. This percentage is often sufficient because benefits are typically tax-free when premiums are paid with after-tax dollars, effectively replacing a larger portion of your net income.
While core requirements generally remain stable, it’s wise to review your specific policy and any updated state or federal regulations for 2026. Insurers may adjust underwriting criteria, and definitions of disability can vary, impacting eligibility for new policies.
Short-term covers temporary periods (weeks to months), often employer-provided. Long-term covers extended or permanent disabilities (years to retirement). Most financial experts recommend having both, as they address different needs and waiting periods for comprehensive income protection.
Yes, self-employed individuals can and should obtain individual disability insurance. It’s even more critical as they lack employer-sponsored benefits. Policies are tailored to self-employment income, providing essential income replacement if they can’t work due to illness or injury.
Policy riders enhance your basic coverage. For instance, a Cost of Living Adjustment (COLA) rider increases benefits with inflation, while a Future Increase Option (FIO) allows you to boost coverage without new medical exams. They add cost but offer greater customization and long-term value.
Conclusion
As we navigate 2026, the importance of understanding and securing your disability insurance benefits cannot be overstated. This essential financial tool provides a critical safety net, protecting your income and ensuring your financial stability if you become unable to work. By carefully evaluating policy types, understanding eligibility and claims processes, and proactively maximizing your coverage, you can build a robust defense against life’s uncertainties. Integrating disability insurance into your overall financial plan is a responsible step toward safeguarding your future and achieving lasting peace of mind.
