Inflation Hedging Strategies for 2026: Protect Your Savings
Anúncios
Understanding robust inflation hedging strategies is crucial to protect your savings from a potential 4% rise as 2026 approaches, ensuring your financial stability in a changing economic landscape.
As we navigate the complexities of the modern economy, the specter of rising inflation consistently looms large. For 2026, many financial analysts are projecting a potential 4% rise in inflation, a figure that, if realized, could significantly erode the purchasing power of your hard-earned savings. This makes understanding and implementing effective inflation hedging strategies not just prudent, but essential for safeguarding your financial future. This article will explore various approaches to shield your wealth from inflationary pressures, providing actionable insights for investors and savers alike.
Anúncios
Understanding Inflation and Its Impact on Your Savings
Inflation, at its core, is the rate at which the general level of prices for goods and services is rising, and consequently, the purchasing power of currency is falling. A 4% inflation rate means that what $100 buys today will cost $104 next year, effectively diminishing the value of your cash holdings and fixed-income investments.
The impact of inflation extends beyond just the cost of everyday items. It silently erodes the real return on your investments, particularly those in traditional savings accounts or low-yielding bonds. Over time, this can significantly delay or even derail your financial goals, from retirement planning to saving for a down payment on a home. Recognizing this threat is the first step toward building a resilient financial portfolio.
Anúncios
The Silent Thief: How Inflation Erodes Wealth
Many individuals underestimate the cumulative effect of even moderate inflation. It’s not just about today’s prices; it’s about the long-term erosion of wealth. Understanding this “silent thief” helps in prioritizing proactive financial measures.
- Reduced Purchasing Power: Your money buys less over time.
- Lower Real Returns: Investment gains are offset by rising costs.
- Increased Cost of Living: Everyday expenses become more burdensome.
- Uncertainty for Future Planning: Financial goals become harder to achieve.
In essence, inflation acts as a continuous tax on your savings, making it imperative to employ strategies that not only preserve capital but also allow it to grow at a rate that outpaces the rising cost of living. Ignoring inflation is akin to allowing a slow leak in your financial bucket, leading to significant losses over the years.
Real Assets: A Tangible Defense Against Inflation
When inflation heats up, tangible assets often become more attractive. These “real assets” derive their value from their physical properties and tend to perform well because their prices often rise with inflation. Investing in real assets can provide a strong hedge against the devaluation of currency.
Real estate, for instance, has historically been a robust inflation hedge. As prices for goods and services increase, so do property values and rental income. This dual benefit allows investors to not only maintain but potentially grow their wealth in an inflationary environment. However, real estate requires significant capital and can be illiquid.
Exploring Real Estate and Infrastructure
Beyond direct property ownership, real estate investment trusts (REITs) offer a more liquid way to invest in real estate. These publicly traded companies own, operate, or finance income-producing real estate across various sectors. Infrastructure projects, such as toll roads, utilities, and communication towers, also tend to have inflation-linked revenue streams, making them attractive.
- Direct Real Estate: Ownership of residential or commercial properties.
- REITs (Real Estate Investment Trusts): Publicly traded real estate portfolios.
- Infrastructure Funds: Investments in essential public services.
Another powerful real asset class is commodities. These raw materials – such as gold, silver, oil, and agricultural products – often see their prices increase during inflationary periods due to rising demand and production costs. Gold, in particular, has long been considered a safe haven asset and a traditional hedge against inflation and economic uncertainty.
Inflation-Protected Securities and Treasury Bonds
For those seeking a more direct and government-backed approach to inflation hedging, Treasury Inflation-Protected Securities (TIPS) are an excellent option. These are special bonds issued by the U.S. Treasury that are indexed to inflation, providing a built-in mechanism to protect your principal and interest payments from rising prices.
TIPS work by adjusting their principal value based on changes in the Consumer Price Index (CPI). When inflation rises, the principal value of the TIPS increases, and consequently, the interest payments (which are a fixed percentage of the principal) also increase. This ensures that the purchasing power of your investment is preserved over time, making them a cornerstone of many inflation-hedging portfolios.
Understanding TIPS Mechanics
The mechanics of TIPS can seem complex, but their protective nature is straightforward. The principal adjustment means that if you hold a TIPS bond to maturity, you are guaranteed to receive at least your original principal amount, or your inflation-adjusted principal, whichever is greater. This feature is invaluable in an environment where inflation is a significant concern.
- Principal Adjustment: Value increases with CPI.
- Fixed Interest Rate: Applied to the adjusted principal.
- Guaranteed Principal: Original or adjusted, whichever is higher at maturity.
While TIPS offer robust protection, it’s important to remember that their real yield (the yield after inflation adjustment) can be low, especially in periods of low inflation expectations. However, their primary purpose is capital preservation in real terms, making them highly effective when inflation is a threat, such as the projected 4% rise for 2026.
Commodities and Precious Metals: Traditional Hedges
Commodities and precious metals have long been recognized as powerful tools in an investor’s inflation-hedging arsenal. Their intrinsic value and often inverse relationship with the dollar make them attractive during periods of economic uncertainty and rising prices. Investing in these assets can provide a tangible store of value that traditional currencies might lack.
Gold, in particular, stands out as a historical inflation hedge. Its scarcity, universal acceptance, and lack of correlation with other financial assets make it a preferred choice for many investors looking to preserve wealth. Silver, often referred to as “poor man’s gold,” also offers similar benefits, with industrial demand adding another layer to its value proposition.
Diversifying with Energy and Agriculture
Beyond precious metals, energy commodities like crude oil and natural gas, and agricultural commodities such as wheat and corn, also tend to perform well during inflationary periods. Rising input costs and increased global demand often push up their prices, providing a natural hedge against inflation. Investing in these can be done through direct futures contracts, commodity ETFs, or stocks of companies involved in their production.
- Gold & Silver: Safe haven assets with intrinsic value.
- Energy Commodities: Oil, natural gas, often rise with inflation.
- Agricultural Products: Wheat, corn, and other foodstuffs.
It’s crucial to approach commodity investing with caution, as these markets can be highly volatile. A diversified approach, combining different types of commodities and utilizing various investment vehicles, can help mitigate risks while still capturing the inflation-hedging benefits. The key is to allocate a portion of your portfolio to these assets, not to go “all in.”
Equity Strategies: Finding Inflation-Resistant Companies
While often seen as vulnerable to rising interest rates that accompany inflation, certain equities can actually thrive in an inflationary environment. The key lies in identifying companies that possess strong pricing power, meaning they can pass on increased costs to consumers without significantly impacting demand for their products or services. These companies often operate in essential sectors or have strong brand loyalty.
Companies in sectors such as consumer staples, utilities, and healthcare often demonstrate this pricing power. People will continue to buy food, use electricity, and seek medical care regardless of slight price increases. Furthermore, businesses with low capital intensity and high-profit margins are better positioned to weather rising input costs.
Identifying Strong Pricing Power and Essential Services
Another strategy involves investing in companies that benefit directly from rising commodity prices, such as energy producers or mining companies. As the cost of their output increases, so do their revenues and profits, providing a natural hedge against inflation. This approach requires careful research into specific industries and companies.
- Consumer Staples: Companies selling essential goods.
- Utilities: Providers of essential services like electricity and water.
- Healthcare: Demand remains relatively inelastic.
- Commodity Producers: Benefit from rising raw material prices.
Dividend-paying stocks, particularly those with a history of increasing their dividends, can also offer a partial hedge. While not directly indexed to inflation, consistent dividend growth can help offset the erosion of purchasing power over time. The careful selection of equities can make them a valuable component of an inflation-hedging strategy.
Diversification and Portfolio Rebalancing for 2026
The most effective defense against inflation, or any market uncertainty, is a well-diversified portfolio. Relying on a single asset class, no matter how strong its historical performance as an inflation hedge, exposes you to unnecessary risk. A diversified approach spreads your investments across various asset classes, reducing the impact of any single asset’s poor performance.
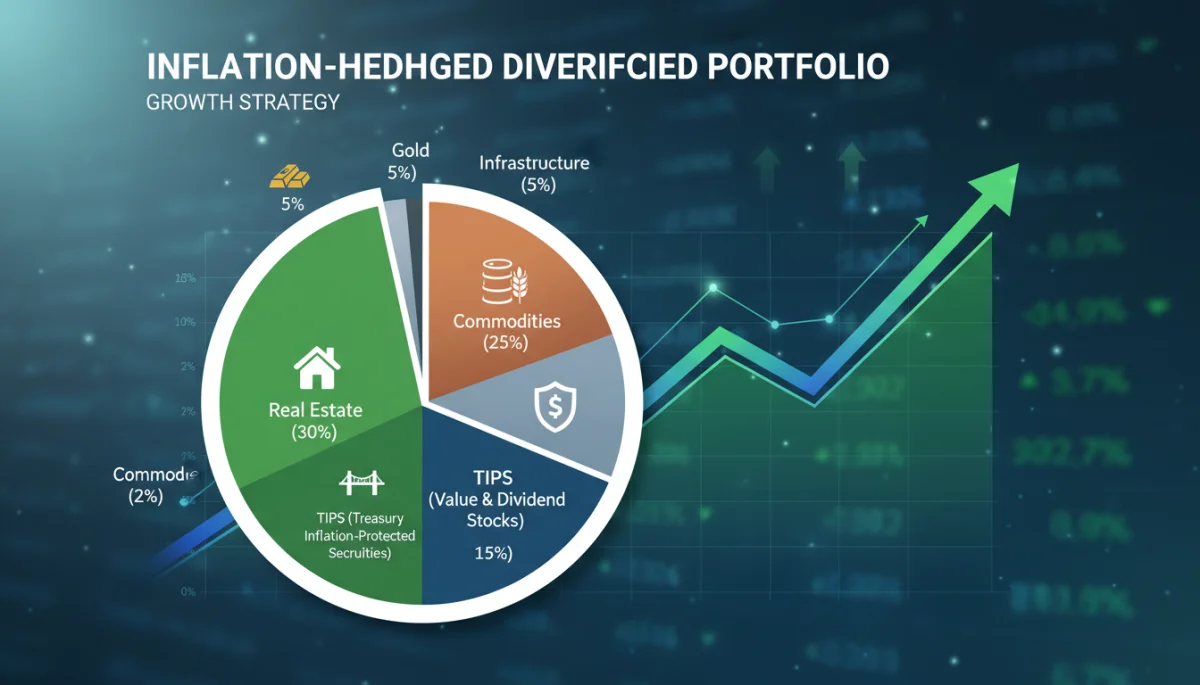
For 2026, with a projected 4% inflation rate, a balanced portfolio might include a mix of real assets like real estate and commodities, inflation-protected securities such as TIPS, and carefully selected equities of companies with strong pricing power. The specific allocation will depend on your individual risk tolerance, investment horizon, and financial goals.
The Importance of Regular Portfolio Review
Diversification isn’t a one-time task; it’s an ongoing process. Regular portfolio rebalancing is crucial to ensure your asset allocation remains aligned with your objectives and market conditions. As some assets perform better than others, their weight in your portfolio will shift, potentially exposing you to unintended risks.
- Asset Allocation: Spreading investments across different classes.
- Risk Mitigation: Reducing impact of single asset underperformance.
- Periodic Rebalancing: Adjusting portfolio to maintain desired allocation.
- Adapting to Market Changes: Staying agile in a dynamic economy.
Rebalancing involves selling off some of the assets that have performed well to buy more of those that have underperformed, bringing your portfolio back to its target allocation. This disciplined approach not only helps manage risk but also enforces a “buy low, sell high” strategy, which can enhance returns over the long term, especially in a fluctuating inflationary environment.
Alternative Strategies and Financial Planning Considerations
Beyond traditional investment vehicles, there are several alternative strategies and financial planning considerations that can enhance your protection against inflation. These often require a deeper understanding of financial markets or specific expertise but can offer significant benefits in a high-inflation environment.
One such strategy involves investing in private equity or venture capital, which can offer exposure to businesses with high growth potential and often less correlation to public markets. However, these investments are typically illiquid and carry higher risks. Another area is private credit, which can provide higher yields and floating-rate structures that adjust with interest rates, offering a natural hedge.
Considering Private Markets and Debt
For those with a higher net worth, direct investments in businesses or specialized funds focusing on infrastructure, timberland, or farmland can also be powerful inflation hedges. These assets have tangible value and often generate income streams that are linked to inflation, providing both capital appreciation and yield.
- Private Equity/Venture Capital: High growth, less correlation.
- Private Credit: Higher yields, floating rates.
- Direct Real Asset Investments: Timberland, farmland.
From a personal finance perspective, reducing debt, especially variable-rate debt, becomes even more critical during inflationary periods. As interest rates rise to combat inflation, the cost of servicing such debt can increase significantly. Conversely, locking in fixed-rate debt when rates are low can be a smart move, as inflation will effectively reduce the real value of those future payments. Moreover, investing in yourself through education and skill development can increase your earning potential, providing a personal hedge against rising costs.
| Key Strategy | Brief Description |
|---|---|
| Real Assets | Invest in tangible assets like real estate and infrastructure whose values often rise with inflation. |
| TIPS | Treasury Inflation-Protected Securities adjust principal with CPI, safeguarding purchasing power. |
| Commodities | Precious metals (gold, silver) and raw materials (oil, agriculture) often appreciate with inflation. |
| Equity Selection | Focus on companies with strong pricing power or those benefiting from rising commodity prices. |
Frequently Asked Questions About Inflation Hedging
Inflation hedging involves investing in assets designed to retain or increase in value during periods of rising prices. For 2026, with a projected 4% inflation rate, it’s crucial to protect savings from erosion of purchasing power, ensuring financial goals remain achievable.
Yes, real estate is often considered a strong inflation hedge. Property values and rental income tend to rise with inflation, providing a tangible asset that preserves wealth. REITs offer a more liquid way to invest in this sector.
TIPS are government bonds whose principal value adjusts with the Consumer Price Index (CPI). As inflation rises, the principal increases, leading to higher interest payments and protecting your investment’s purchasing power over time.
Gold and silver are traditional inflation hedges due to their intrinsic value. Energy commodities like oil and natural gas, along with agricultural products, also tend to see price increases during inflationary periods, offering diversification.
Certain stocks can. Look for companies with strong pricing power that can pass on increased costs to consumers, such as those in consumer staples, utilities, healthcare, or commodity-producing sectors. Dividend-growing stocks can also offer a partial hedge.
Conclusion
Protecting your savings from inflation, especially with a potential 4% rise projected for 2026, demands a proactive and well-thought-out strategy. By understanding the various inflation hedging tools available – from real assets and inflation-protected securities to carefully selected equities and commodities – you can build a resilient portfolio. Diversification and regular rebalancing are not merely good practices but essential disciplines in an inflationary environment. While no strategy offers guaranteed protection, a comprehensive approach can significantly mitigate the erosive effects of rising prices, ensuring your financial security and helping you achieve your long-term goals. Your digital journey begins here, equipped with the knowledge to safeguard your financial future.
